Financing an ADU Is Easier Than Most People Think
Many homeowners assume an accessory dwelling unit (ADU) is only possible if they can pay for everything out of pocket. In reality, most ADU projects in California are financed — and lenders have become far more comfortable with ADU loans as backyard homes have gone mainstream.
Option 1: Home Equity Loan or HELOC
If you've built up equity in your home, a home equity loan or home equity line of credit (HELOC) is one of the most common ways to fund an ADU. You borrow against the equity you already have, often at rates lower than a construction loan. A HELOC gives you flexibility to draw funds as the project progresses.
Option 2: Cash-Out Refinance
Refinancing your existing mortgage for a larger amount lets you pull cash out for the ADU project while potentially restructuring your loan. This option makes the most sense when current rates are favorable compared to your existing mortgage — talk to your lender about the math before deciding.
Option 3: Construction or Renovation Loan
Construction loans and renovation-style loans are designed for exactly this kind of project. The lender releases funds in draws tied to project milestones, which keeps spending disciplined. Some lenders count projected rental income from the ADU toward your qualification — a big deal for homeowners building a unit to rent out.
Option 4: State and Local Programs
California has periodically offered grants and forgivable loans for pre-development costs like plans and permits, and some cities and counties run their own ADU assistance programs. These programs change often and usually have income limits, so check your city and county housing offices for what's currently available.
Questions to Ask Before You Borrow
- Can the lender count future ADU rental income toward my qualification? Not all of them can — and the ones that do usually want to see a lease or rental estimate.
- Does the loan allow draws as construction progresses? Matching funding to the build schedule avoids paying interest on money you don't need yet.
- What does the appraisal assume? An appraiser familiar with ADUs can make a real difference in how much equity the lender recognizes.
Start With the Project, Then the Loan
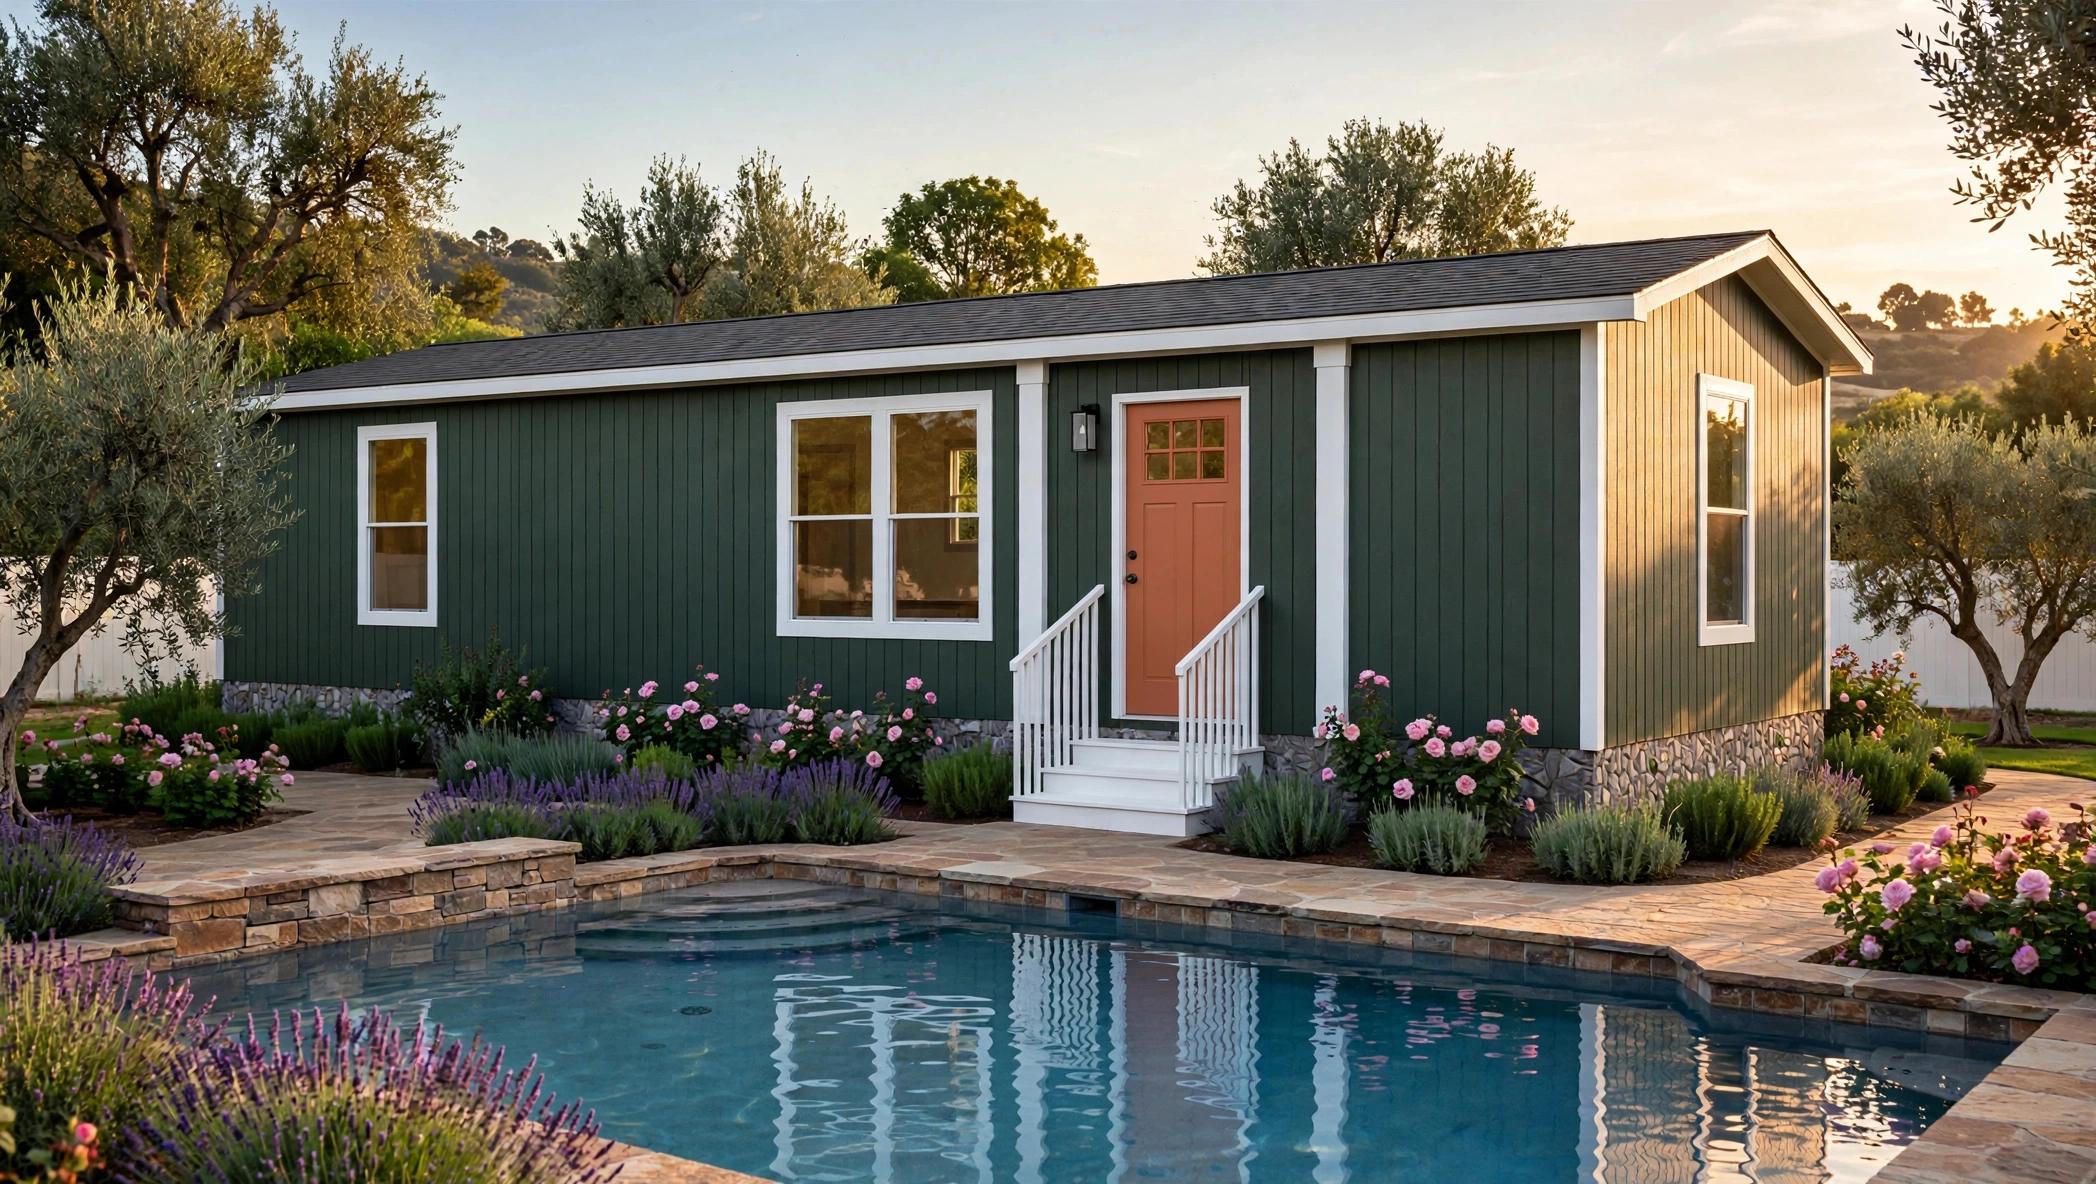
Lenders want to see a clear plan: which model you're building, where it sits on your lot, and a realistic all-in scope. At American Dream ADU, we walk homeowners through exactly that — so when you sit down with a lender, you're financing a defined project, not a vague idea.
Ready to see what's possible on your lot? Schedule a free consultation and get a clear picture of your options — no pressure, no obligation.
---
Please note: This article is for general information only. Rules vary by county and city — always check with your local county or city planning office for the specific rules that apply to your property before making decisions.